We welcome the $10 million trade finance agreement between the African Development Bank Group (AfDB) and Family Bank Limited as a practical intervention in one of Africa’s persistent economic constraints: the difficulty productive businesses face in obtaining affordable foreign-currency financing.
Signed on 2 October at the AfDB’s East Africa Regional Office, the Trade Finance Line of Credit will enable Family Bank to finance eligible small and medium-sized enterprises (SMEs) and local companies in Kenya. Manufacturing, agriculture, healthcare and renewable energy businesses will receive priority, alongside enterprises owned by women.
We consider the agreement important because productive businesses cannot generate employment, increase output or compete across borders when they cannot finance essential imports, equipment, raw materials and other operational inputs. Access to finance is not merely a banking concern; it is a condition for industrial development and trade competitiveness.
The facility addresses a specific financing gap. Smaller businesses frequently struggle to secure trade finance because of limited collateral, short operating histories and the risks associated with cross-border transactions. These constraints can prevent otherwise viable enterprises from purchasing supplies, fulfilling orders and participating in regional value chains.
By working through Family Bank’s domestic network and knowledge of the Kenyan market, the AfDB is using an established financial intermediary to direct capital towards businesses that might otherwise struggle to access international trade financing. We regard this approach as commercially relevant because the effectiveness of development finance depends not only on the capital provided but also on the institutions responsible for deploying it.
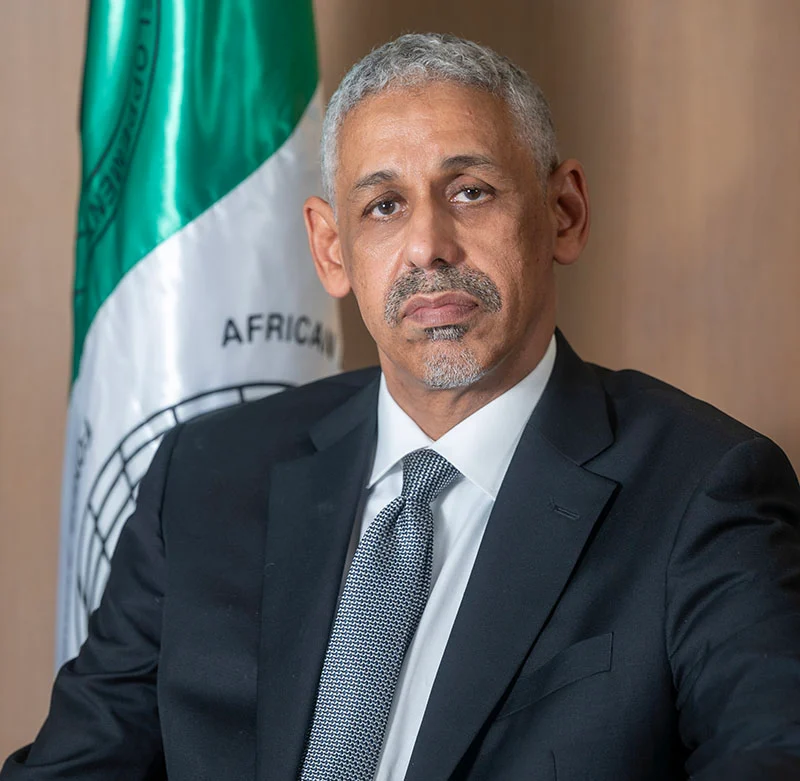
AfDB East Africa Director-General, Alex Mubiru, captured the underlying principle when he said: “A line of credit becomes meaningful only when it becomes a line of opportunity for a business.”
We agree. A credit facility becomes economically valuable when businesses can use it to purchase inputs, maintain production, fulfil contracts and generate sustainable revenue. The amount committed is only the starting point; the resulting commercial activity determines its wider significance.
Mubiru stated: “Through Family Bank’s local reach, we expect this facility to support enterprises that are producing, trading, creating jobs and strengthening Kenya’s value chains.”
We consider this emphasis on local reach particularly important. Development finance must move beyond established large companies and reach smaller enterprises with viable products, credible business models and the capacity to generate employment. Otherwise, access to capital risks remaining concentrated among businesses already positioned to obtain it.
The agreement also supports Kenya’s participation in the African Continental Free Trade Area (AfCFTA). By helping businesses finance productive inputs and cross-border transactions, the facility could strengthen regional supply chains and increase trade among African countries. We should recognise this as an important objective because continental trade cannot flourish on political declarations alone. Businesses need finance, reliable logistics, predictable regulations and commercially viable markets.
However, we must distinguish the facility’s stated objectives from outcomes that are yet to be demonstrated. The announcement provides no breakdown of the number of businesses expected to benefit, the financing terms, the expected disbursement schedule or the employment opportunities projected. Nor does it establish how much additional trade the facility will generate.
We should assess the programme through transparent performance indicators, including the number and diversity of beneficiary businesses, financing costs, repayment performance, additional production, jobs created and export transactions supported. We should also examine whether women-owned enterprises and smaller businesses outside established commercial centres receive meaningful access.
We believe the agreement offers a useful model for African development finance, but replication should depend on demonstrated results rather than the headline value of the credit line. Financial institutions must ensure that eligible enterprises understand the application process, that lending decisions remain commercially sound and that financing reaches productive activities without creating unsustainable debt burdens.
For investors, the arrangement illustrates how development institutions and local banks can combine international capital with domestic distribution networks to address market gaps. For businesses, it offers a potential route to financing that could strengthen production and trade. For policymakers, it reinforces the need to improve the broader conditions under which enterprises operate.
Ultimately, we must judge the AfDB–Family Bank partnership by what it delivers beyond the signing ceremony.
We need more such facilities across Africa, but we need even more evidence that they are reaching businesses, expanding productive capacity and converting access to finance into measurable economic gains.
Discover more from StakeBridge Media
Subscribe to get the latest posts sent to your email.