Jennete Ugo Anya
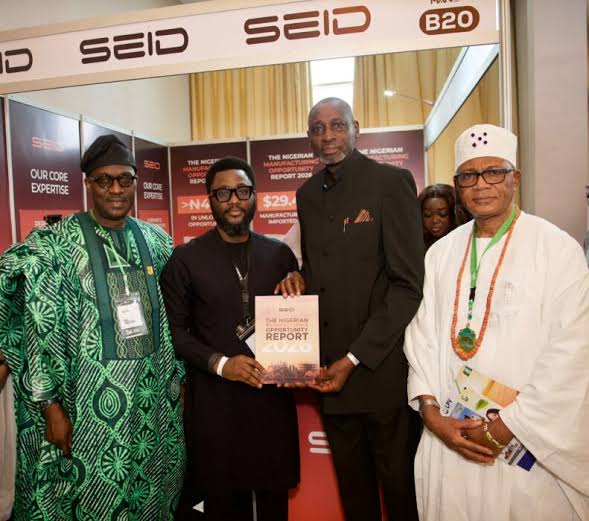
SEID, a marketing communications and market intelligence firm, launched its Nigerian Manufacturing Opportunity Report 2026 at the Manufacturers Association of Nigeria (MAN)’s 54th Annual General Meeting (AGM), identifying more than N40 trillion in untapped manufacturing opportunities. The report estimates that imports met 64 percent of Nigeria’s manufactured goods demand in 2025, representing a $29.4 billion market. It also records manufacturing’s contribution to gross domestic product (GDP) declining from 8.42 percent in 2023 to 8.05 percent in 2025.
DECISION HIGHLIGHT
The report identifies a substantial gap between domestic demand and local production. Closing it requires more than import substitution: Nigeria must improve industrial competitiveness through reliable energy, logistics, infrastructure, technical skills and stronger value chains.
DECISION MEMO
Nigeria’s manufacturing challenge is increasingly defined by the gap between market demand and domestic capacity. The N40 trillion opportunity identified by SEID suggests considerable room for local producers, but the scale of imports shows that demand alone has not translated into sufficient industrial output.
SEID Managing Partner, Tubosun Akeju, said: “Nigeria already has the demand and some of the industrial strengths required to build a much stronger manufacturing sector.
“The opportunity is to understand where those strengths exist, deepen them, and build the competitiveness required to capture more value locally and compete beyond our borders. The Nigerian Manufacturing Opportunity Report 2026 provides decision-makers with the insights on opportunities that are most immediate, where Nigeria is already making progress and what needs to be done better to unlock greater value.”
The report argues for a geographically and sectorally differentiated approach rather than a uniform industrial policy. The South-West remains Nigeria’s largest manufacturing zone, while other regions have strengths in food and agro-processing, textiles, chemicals, pharmaceuticals, cement, steel and light manufacturing.
This distribution matters because industrial investment is more likely to build scale when it strengthens existing capabilities, supplier networks and specialised production clusters. The report’s five subsectors are light manufacturing and packaging; food and agro-processing; textiles, apparel and leather; chemicals and pharmaceuticals; and cement and steel.
However, the decline in manufacturing’s GDP contribution indicates that existing industrial strengths have not translated into a larger economic share. Nigeria must therefore address the conditions constraining production, while helping domestic manufacturers improve quality, scale and cost competitiveness.
The export dimension is equally important. The report places Nigeria’s manufacturing export intensity below the Sub-Saharan African average, suggesting that local industry must compete beyond the domestic market. Gas-linked fertiliser production illustrates how feedstock availability, scale and industrial capacity can create competitive advantages, but such advantages require supporting infrastructure and efficient value chains.
DATA BOX
- Untapped manufacturing opportunities: More than N40 trillion.
- Manufactured goods demand met by imports in 2025: 64 percent.
- Import market represented: $29.4 billion.
- Manufacturing contribution to GDP: 8.42 percent in 2023; 8.05 percent in 2025.
- Concentration: Three of five major subsectors account for approximately 71 percent of manufacturing output.
- Report: Nigerian Manufacturing Opportunity Report 2026, launched by SEID.
WHO WINS / WHO LOSES
Potential winners: Domestic manufacturers, investors, suppliers and workers if local production expands competitively.
Potential losers: Import-dependent businesses could face stronger domestic competition, while manufacturers may continue losing market share if production costs and infrastructure constraints remain unresolved.
POLICY SIGNALS
Industrial policy should reflect regional specialisation and value-chain strengths. Reliable power, logistics, infrastructure, technical skills and export competitiveness are essential to converting identified opportunities into production.
INVESTOR SIGNAL
The report provides a framework for identifying investment opportunities across five manufacturing subsectors and state-level industrial clusters. Investors should assess market demand alongside input availability, operating costs, infrastructure and export potential.
RISK RADAR
The N40 trillion opportunity is not guaranteed revenue. High production costs, infrastructure deficits, weak value-chain integration and limited export competitiveness could prevent domestic manufacturers from capturing the market currently served by imports.
Jennete Ugo Anya is a journalist and researcher with interests across Nigeria’s economy, public policy, business, MSMEs, development and strategic communications, Foreign direct investments, development finance institutions.
Discover more from StakeBridge Media
Subscribe to get the latest posts sent to your email.